Whether you’re a seasoned investor or a novice entrepreneur, commercial real estate rates will always be a focal point guiding your investment decisions.
This article will simplify commercial mortgage rates, shedding light on key points of consideration and practical strategies to optimize your investments.
Current commercial real estate rates.
As of October 2026, we’re seeing rates that range from about 6.44% to 15%, depending on the asset type and specific circumstances of the loan.
Key elements of commercial real estate rates.
Commercial mortgage rates are determined based on a combination of market factors, property-specific factors, the stance of the lender and borrower, and the loan structure.
Market conditions
Overall market conditions play a role in determining commercial real estate rates. Several macroeconomic factors contribute to rate fluctuations.
Economic factors
Commercial mortgage rates are influenced by broader economic conditions, such as inflation, economic growth, and the overall health of the economy.
Interest rates
The general level of interest rates in the economy—often indicated by benchmark rates such as the prime rate, SOFR (Secured Overnight Financing Rate), or the U.S. Treasury yields—can impact the rates offered by lenders.
It's important for borrowers to carefully consider these factors and work with lenders to secure the most favorable terms, based on their financial situation and the specific details of the commercial property transaction.
Property-specific factors
The nature of the property itself will significantly impact mortgage rates, namely property type and location will also impact your final rate.
Property type
Different types of commercial properties may have varying risk profiles, affecting the interest rates. For example, rates for office spaces might differ from those for industrial properties.
Property type
Current starting rate
Multifamily loans
6.44%
Mobile home parks
6.66%
Retail
7.42%
Office buildings
7.42%
Industrial properties
7.42%
Self-Storage
7.42%
Medical properties
7.42%
Hospitality properties
7.00%
CMBS loans
7.13%
Bridge loans
9%
Location
The location of the property can impact rates. Properties in high-demand or economically thriving areas may have lower rates compared to those in less desirable locations.
Borrower's creditworthiness
Your creditworthiness and general financial situation will impact your rate.
Credit score
The creditworthiness of the borrower is a crucial factor. Lenders assess the borrower's credit history, financial stability, and debt-to-income ratio to determine the risk associated with the loan.
Business financials
Lenders may also evaluate the financial health and performance of the business occupying the commercial property.
Loan-to-value (LTV) ratio
The loan-to-value (LTV) ratio is the percentage of the property’s value that you’re looking to finance with the loan.
If you’re looking for a high LTV ratio, it means you’re seeking to borrow a larger portion of the property’s value, which could present a higher risk to the lender. Because of this increased risk, you may find that higher LTV ratios are typically accompanied by higher commercial mortgage rates.
Loan term and amortization period
Rates will also vary based on the length of the loan and the repayment schedule.
Loan term
The length of the loan term can influence the interest rate. Shorter-term loans may have lower rates but higher monthly payments, while longer-term loans might have slightly higher rates but lower monthly payments.
Amortization period
The time it takes to repay the loan (i.e. the amortization period) can also impact the interest rate. A longer amortization period may result in a higher overall interest cost.
Lender's policies and competition
Every lender's rates are impacted by its investment portfolio and competition.
Lender policies
Each lender may have its own criteria and policies, impacting the rates they offer. Some lenders may specialize in certain property types or industries.
Competition
The competitive landscape among lenders can affect rates. Borrowers may get more favorable rates if lenders are competing for their business.
Fixed vs. variable rates
Commercial mortgage rates can be fixed (i.e. unchanging throughout the loan term) or variable (i.e. fluctuating based on market conditions). Fixed rates provide stability, while variable rates may offer initial cost savings but involve more risk. Borrowers should choose the type of rate that aligns with their financial goals and risk tolerance.
SBA 504 loan rates: An option for small businesses.
For entrepreneurs seeking to finance major fixed assets like real estate or equipment, the Small Business Administration's (SBA) 504 loan can be a great option. The SBA 504 loan is known for its competitive and predictable rates, making it a popular choice among borrowers.
Fixed-rate loans under this program are tied to U.S. Treasury bonds, which typically carry some of the market's best rates.
The rates for SBA 504 loans are set when the SBA sells the bond to fund the loan. This means borrowers can lock in a low, long-term fixed rate, protecting their business from future interest rate increases. The 10-year Treasury rate as of October 2026 is around 5.22%.
It's also essential to understand that SBA 504 loan rates include two different loans—one from a Certified Development Company (CDC) and one from a bank or other financial institution.
The CDC loan, which covers up to 40% of the total project cost, has a fixed interest rate.
In contrast, the bank loan, covering 50% or more of the total project cost, can have a variable or fixed rate, depending on the specifics of the agreement.
Remember, despite these attractive rates, it's important to consider all aspects of your financial situation and business goals before deciding on a loan product. Consult with financial professionals to make sure you're making the best choice for your business.
Wrapping up
By familiarizing yourself with the primary elements that influence these rates, and keeping an eye on current market conditions, you’re already on the right path.
Whether you're considering a traditional commercial mortgage or exploring options like the SBA 504 loan, remember that the best choice will depend on your unique financial situation and business goals.
Lendio funds small businesses across the full credit spectrum, from limited credit histories to excellent credit.
A study of new financing relationships from January 1 to September 1, 2026 shows just how broad that reach really is: 14.7% were businesses with limited or building credit (below 580), accounting for 4.6% of all dollars funded. Another 51.2% of relationships were businesses in the fair-to-good range (580-699), representing 37.4% of dollars funded. 34.1% of relationships were businesses with strong credit (700+), representing 58% of dollars funded.
Every tier of credit has substantial volume in financing through Lendio’s SMB lending platform.
What changes with your credit profile isn’t whether Lendio works for you, it’s which of the network’s 100+ lenders and products fit you best, from specialized cash-flow lenders to banks and financial institutions. A single direct lender, or a narrower marketplace, can really only serve one part of the spectrum well. Lendio was built to cover as much of it as possible.
This article explains how credit actually fits into what Lendio's lender network evaluates, what the data shows about who gets funded at every credit level, and where to go next depending on your situation. It doesn't determine your approval odds or guarantee a specific outcome. Those factors depend on the lender, the product, and your full financial picture.
Credit score isn’t the whole story.
Credit score is just one input among several that Lendio’s network weighs, alongside time in business, monthly revenue, industry, cash flow consistency, and the specific financing product being requested.
That’s the reason that the loan marketplace model exists for business financing: no single or direct lender can serve the full range of small businesses well, so marketplaces create an opportunity for small businesses to see options among a diverse range of lenders. Lendio builds on that standard one-to-many marketplace model within its SMB lending platform, utilizing proprietary AI models and data points to intelligently match each business to the right lenders for its specific profile.
Beyond the tier breakdown above, a few things stand out at each end of the credit spectrum.
For businesses with strong credit (700+):
Average loan size scales sharply with credit score. Businesses in the 800+ range receive roughly 43 times the average loan amount of businesses in the 500-and-below range through Lendio.
A defined tier of established, high credit, high-revenue businesses, averaging a 706 credit score and approximately $215,000 in monthly sales accounts for nearly 40% of total dollars funded across the network.
For businesses with limited or lower credit:
The product most commonly used towards this end of the spectrum (revenue-based financing) is underwritten primarily around consistent cash flow and revenue, not credit history. It exists specifically because credit score is a poor predictor of repayment ability for a business with strong, steady cash flow but a limited or damaged credit file.
Loan amounts tend to grow substantially over a continued relationship. Among businesses with more than one closed loan through Lendio, 58.5% saw their loan size increase over time, with a typical gain of 20-25%. Funded history, not just a rising credit score, is what opens up more capital over time.
Put together, Lendio isn’t a platform that happens to work for good credit, or one that happens to work for developing credit. Both are core to how the network is built, just routed to different products and lenders.
What Lendio's lender network generally evaluates.
Individual lenders in the network set their own criteria, and requirements vary by product. In general, these categories come up across most business financing decisions:
Time in business. Operating history signals stability. Newer businesses aren't excluded, but they typically have fewer product options than businesses with two or more years of operating history.
Revenue and cash flow. For many financing products, this matters as much as, or potentially more than, credit score. Lenders want to see that incoming revenue can reasonably support repayment, not just that a credit score clears a set bar.
Credit profile. This includes personal credit history, business credit history where one exists, and payment behavior on existing obligations. Both personal and business credit can factor in, particularly for newer businesses that haven't built an independent business credit file yet. Across the network, credit checks are commonly done as a soft pull at the initial application stage. Comparing offers through Lendio doesn’t automatically generate multiple hard queries on a business owner’s credit report: a harder pull, where it applies, typically only happens later closer to funding.
Documentation completeness. This includes bank statements, tax returns, and financial statements. How much is required varies significantly by loan size and product type.
Industry. Certain industries face restrictions or added scrutiny across a meaningful share of the network. Most commonly gambling, adult entertainment, firearms, cannabis, oil and gas, and mining-related businesses, along with closer review for higher-risk category businesses. These restrictions vary significantly by lender; an industry excluded by one lender is often served by another, which is part of what a multi-lender network is built to handle.
Ownership and guarantee. Many lenders require whoever personally guarantees the loan to hold a minimum ownership stake in the business, commonly in the 20%-51% range across the network. This can run anywhere from 1% to a full 100%, depending on the lender and product.
Network breadth. Because Lendio works with 100+ lenders rather than one underwriting standard, the practical effect is a wider range of acceptable profiles than any single lender could offer on its own, at every credit level, not just on top of it.
The categories above interact: a business’s industry, ownership structure, and documentation readiness all shape which lenders are actually available before credit score even enters the picture. But credit score alone still reshapes access substantially. Looking at Lendio's network of lender products directly (holding time in business at a typical 2+ years): roughly 14% of network products are accessible at a 500 credit score, climbing to 45% at 600, 79% at 700, and leveling off around 81% from 750 upward. The remaining fifth is generally held back by factors like industry restrictions rather than credit score itself.
Each of these varies in weight depending on the product. A short-term line of credit and an SBA loan evaluate a very different mix.
How credit score commonly lines up with financing types.
Looking at recently funded data, credit profiles cluster into a clear pattern by financing products. It’s important to note, however, this reflects tendencies in a large dataset, not a pass/fail list or a set of minimums.
Financing product type
Where it commonly shows up in the credit range
What else typically matters more here
Short-term or revenue-based financing
Full range, including limited or lower credit histories
Consistent revenue and cash flow
Business line of credit
Skews towards mid-to-upper credit ranges, especially for repeated/ renewal use
Time in business, revenue consistency
Term loans
Skews towards stronger credit profiles
Revenue size, use of funds, documentation
SBA loans
Tends toward higher end of the credit range
Debt-service coverage, time in business, documentation depth
A lower credit score doesn’t rule out a term loan, and strong credit doesn’t guarantee an SBA loan without meeting its other criteria. Even the SBA’s own standard has moved in this direction: As of March 2026, the SBA no longer mandates a specific FICO SBSS pre-screening score for 7(a) Small Loans, having shifted to lender specific credit models and a debt-service coverage requirement instead.
How credit score affects your terms.
Credit score reshapes financing on both ends of the spectrum, just not in the same way.
If your credit score is strong (700+): Pricing improves, and so does your leverage. The 740+ tier sees the lowest median financing cost of any credit band in the network, and businesses in this range receive roughly 6 competing offers per financing request on average, compared to fewer than 2 for the weakest credit profiles.
If your credit is limited or still building: Access and volume are real. As shown above, this range represents over half of new financing relationships through Lendio and a substantial share of total dollars funding. Pricing does reflect risk the way it does with any lender, and cost per dollar borrowed is higher here than for stronger-credit tiers. Revenue-based financing exists as a real, structurally appropriate product for this profile, not a discount version of a “real” loan. And the data shows a real growth path. Among businesses with more than one closed loan, a majority (58.5%) see their loan size grow over time. Funding history, not a rising credit score, is what opens up more capital over time.
Readiness signals worth knowing before you apply.
A few factors tend to separate businesses that move smoothly through the process from businesses that hit friction, regardless of credit tier:
Having recent bank statements and financials ready, rather than assembling them after a lender requests them.
Knowing your actual monthly revenue and cash flow pattern, not just annual figures. This matters even more if credit history is limited, since it’s often the stronger part of the file.
Understanding which financing product you’re applying for and why, rather than applying broadly and sorting it out later.
Being aware of both personal and business credit standing, since newer businesses in particular are often evaluated on both.
None of these guarantee approval, and gaps in one area don’t automatically disqualify a business. They’re simply the factors that come up most often.
How this varies by program
Requirements differ between an SBA loan, a term loan, a line of credit, and shorter-term financing. That’s true of what’s evaluated, and how heavily credit score factors in relative to revenue and cash flow. Our SBA loan requirements and business line of credit requirements guides go deeper into those products specifically.
Summary and key takeaways.
Lendio’s lender network funds businesses across the full credit spectrum, not primarily one end or the other. Strong-credit businesses often see bigger loans, better pricing, and more options; limited-credit businesses get real access to products built around cash flow rather than credit history, plus a data-backed track record of growing loan amounts as their history builds. Credit score determines which products and lenders make sense for a given business, not whether that business belongs on the platform.
No universal minimum credit score applies across Lendio’s network.
Businesses with limited or building credit (under 580), fair-to-good credit (580-699), and strong credit (700+) each represent a substantial share of Lendio’s funded businesses.
Stronger credit means larger average loan sizes, lower financing costs, and more offers to compare in Lendio’s network
Limited or developing credit doesn’t mean exclusion. It means routing to products built to evaluate cash flow instead, plus a track record of growing loan amounts among returning customers.
Requirements vary meaningfully by product: SBA and term loans skew towards stronger profiles, while other products serve a broader range by design.
This page describes general patterns noted from internal data, not guaranteed outcomes. Individual approval depends on the specific lender and application.
Methodology
Figures on this page are drawn from Lendio’s own closed-loan data and lender network specifications. Different statistics reflect different time periods and borrower populations: new-borrower credit and loan-size figures reflect 2026 activity, network-access figures reflect current lender product specifications, and loan-growth figures reflect a broader multi-year comparison across repeat borrowers. All figures describe historical patterns in Lendio’s data and are not a guarantee of future terms, pricing, or approval for any individual applicant.
Nearly 60% of small businesses that apply for financing don’t receive the full amount they’re seeking, according to the Federal Reserve’s 2026 Report on Employer Firms. Reasons for this can range from operating in a risky industry to a low credit score. But what really shouldn’t be a concern is flubbing the preapproval process because you didn’t have the right documents needed for a small business loan.
Here’s the painful part: if you’re applying to banks or lenders one at a time, you could end up assembling a slightly different document package for every single application.
This is because the documents you’ll need to submit an application to a lender varies based on the type of financing you’re looking at, and the loan amount. For example, business credit cards and revenue-based financing often require less documentation than term loans or lines of credit.
To keep it all straight, and help you prepare to assemble a strong application package, we’ve analyzed the application submission requirements for 100+ lenders across every major financing type in our marketplace, and the documents you’ll need to paint a full business picture lenders can use to make an offer.
We’ll walk you through exactly what you’ll need to provide to apply, and explain why so you’re prepared. We’ll also discuss documentation requirements for a few financing edge cases, like SBA loans.
What documents will you need to apply for a small business loan?
When you apply for small business financing, you’re typically providing information across several categories. Each one gives lenders a fuller picture of your business and your ability to repay. Below is a full list of documents to have on hand for reference, or to submit with your application package, and why each piece matters.
Document
Application section
Submitted with application?
EIN (business tax ID)
Business details
Yes
DBA/ fictitious business name filing
Business details
Yes
Articles of Incorporation or Organization
Business details
Possibly
LLC operating agreement or bylaws
Business details
Possibly
Business bank statements
Business bank statements
Yes, 3-6 most recent statements
Debt schedule
Existing business debt
Yes, if your business has existing loans or debt
Business tax returns
Tax returns
Yes, 2 years
Personal tax returns
Tax returns
Yes, 2 years for each 20%+ owner
Profit & Loss statement (also called income statement)
Business financial documents
Yes
Balance sheet
Business financial documents
Yes
About you, your business, and your ownership structure.
Expect to provide basic information about yourself and your business, along with ownership details. This will include what percentage you own, and whether the business is owned by a majority of U.S. citizens or nationals. Co-owners will need to be listed too, along with their ownership percentage. Keep in mind that additional owners with a significant stake may also be asked for their own tax returns and a soft credit check.
A soft credit check.
Lenders typically request your date of birth and Social Security number to run a soft credit check. A soft credit check won’t affect your credit score. It gives them an early read on your personal credit alongside your business credit profile.
Note: A hard credit pull typically occurs later in the process, closer to closing.
Business bank statements.
Typically 3-6 months of statements are required from your business checking account, whether by connecting your account directly or by providing statements. These show lenders your cash flow patterns, and they need to come from a dedicated business account, not a personal one.
Lendio Tip: Timing is everything. When you apply for financing, block enough time to get your application package ready and submitted quickly, or aim to apply at the beginning of a new month. Otherwise, you may have to go back and pull the most recent month's statement to add to your existing application package.
Tax returns.
Generally 2 years each of business and personal tax returns (personal, for any owner with 20% ownership). These objectively show lenders how much your company makes, how much you draw from the business, and how much money you personally have in the bank. Some lenders want to see profit on your return, or if not profit, a clear path to it. They also want to see that you pay your taxes full and on time.
A debt schedule (if you carry existing debt).
This document outlines every outstanding debt your business has. It includes outstanding balance, interest rate, payment frequency, maturity date, collateral (if any used), and guarantors on the debt (if any).
Profit & Loss Statement and balance sheet.
A P&L, also called an income statement, shows your revenues, expenses, and profit or loss over a specific period. A balance sheet is a snapshot of your assets, liabilities, and equity at a single point in time. Together, they tell a lender what your business is making, spending, owning, and owing. Learn more about income statement vs. balance sheet, and what the key differences are.
What other documents you might need to apply, depending on the type of financing.
The documents above cover what nearly every financing type requires. However, a few financing products ask for a few more details beyond it, and might be worth preparing ahead of time.
Equipment financing wants a quote or invoice from your vendor once you’ve chosen your equipment.
Commercial real estate purchases want a letter of intent, promissory note, and purchase agreement once you have a property under contract.
Invoice factoring, when a lender is underwriting your receivables directly, wants an accounts receivable aging report and your actual outstanding invoices.
SBA loans typically need more, due to additional federal requirements. Our article on applying for an SBA loan goes into more detail on SBA loan documentation requirements.
You may also be asked for a business plan, especially if you’re a newer business or applying for an SBA loan. Lenders reviewing it look at two things: whether the problem you’re solving and your solution to it hold up, and whether you’re a good fit for them. Don’t assume this only applies to tech companies, either. A hair salon solving the simple problem of “there isn’t one within six blocks” is a perfectly sound business plan.
How do document requirements change across different lenders and financing types?
If you’re evaluating lenders individually, or are after a specific type of financing product, keep in mind that there are differences in what each will ask for. We analyzed documentation requirements across our network of 100+ lenders to pinpoint some valuable information for prospective borrowers.
For many financing product types, what a lender asks for will scale with how much you’re requesting. Across term loans, lines of credit, and equipment financing, loan requests that fall under a certain amount (in a band of $75,000-$150,000 depending on the lender), only a fraction of what’s outlined above tends to be necessary to assess whether the lender wants to make an offer. Above the lender-set threshold, the rest of the package comes into play: business tax returns, personal tax returns, a profit and loss statement, a balance sheet, and a debt schedule.
Not every financing type follows this pattern. Business credit cards and revenue-based financing typically stay lighter than others regardless of the amount you’re requesting.
Because of this, having the complete set of application documents on hand before you consider applying will create less friction in the application process, regardless of individual lenders and financing product types.
Let Lendio do the matching for you.
The friction of assessing different lenders, financing types, and documentation requirements is where Lendio’s application shines. Instead of reassembling a slightly different package for every lender you approach, one application that contains the core documents you need gets you in front of our full network of 100+ lenders, spanning every financing type covered above.
Matching happens when you complete and review your application. Input your business information and upload the documentation covered above once, and we compare it against what each lender in our network requires, surfacing offers from the ones who work with businesses like yours, in your industry and at your stage.
You’re guided through the application process, and directed on where and when to upload key details and documentation. And if you aren’t sure whether something applies to your situation, you won’t be figuring it out alone. Every applicant works with a dedicated Funding Expert who can walk you through exactly what’s needed for your application and find you the right lenders, and support your business through the financing process.
No, Lendio does not sell your data to lead generators or brokers. We never have. If you’ve seen claims suggesting otherwise, we want to address them directly, because transparency is how we operate.
This article explains exactly what we do with your information, what actually caused the concerns some borrowers experienced, and what you can do to protect yourself going forward.
What we do with your data.
Lendio is a SMB lending platform. When you apply for business financing, we collect the information necessary to evaluate your application and match you with lenders. This information is things like business details, financial statements, and contact information.
Matching you with lenders. Your application data is shared with the lenders, brokers, and financing providers in our platform as a core function of the service. This is not the same as selling your data. Matched lenders may retain your information even if you don't move forward with them, but you can contact any matched lender directly if you'd like to be removed from their records, or Lendio at [email protected].
Internal operations. Your data is used internally for fraud detection, security, customer support, and product development. We may also use anonymized or aggregated data for business intelligence. In that form, it can no longer be linked back to you.
What “selling data” actually means.
Selling data refers to a company collecting, aggregating, and monetizing personal information about individuals, usually without their knowledge. For a borrower, this typically means your information being sold to parties you never chose to interact with.
Lendio does not participate in data brokering or third-party data sales, and is not a lead generation company. The instances in which your data is used internally and how (and who) it is shared with as part of the application and underwriting process is outlined in Sections 3 and 4 of Lendio’s Privacy Policy.
So if Lendio doesn’t sell data, why were some borrowers receiving unsolicited calls from lenders they’d never heard of? It’s a fair question, and the answer has nothing to do with Lendio’s data practices. In December 2025, we started hearing from borrowers experiencing exactly this, and we investigated immediately.
Our Information Security team conducted a full route forensic audit internally of all data exit points and API routes by our Information Security department, and confirmed there was no internal compromise.
The team then contacted affected borrowers directly to gather more information on the spam calls and also provide details on the results of the audit.
The team also introduced a “Borrower Security Concern” workflow for our support and account teams in order to be able to flag and escalate borrower feedback directly to the InfoSec team for real-time investigation.
“Our job isn’t just to watch the perimeter, it’s to make sure borrowers can trust what happens on our side of it. We audited every data exit point, contacted affected borrowers directly, and built the workflows to make sure concerns like this reach us fast. We didn’t find a breach because there wasn’t one. But we came out of this with a stronger system regardless.” - Director of Information Security, Lendio.
Our team found no security breaches during the audit, but the Information Security team was able to discover the culprit: a well-known but little-understood industry practice called a credit trigger lead.
Understanding credit trigger leads, and how to avoid them.
A credit trigger lead occurs when major credit bureaus like Equifax, Experian, and TransUnion sell your information to other lenders after you apply for credit. When you apply for a loan and the lender pulls your credit report, this notifies the bureau, who then sells your contact information to other lenders as a “trigger lead”.
Oftentimes, other lending competitors will contact you, sometimes within hours, trying to offer a better deal.
Are credit trigger leads legal?
Yes, they are, and you don’t have to explicitly agree to it. Credit bureaus are legally allowed to release your information to paying members of their network. Recent legislation is taking aim at the practice primarily on the consumer mortgage loan side, rather than business-specific loans. The good news is, there are steps you can take to opt out, which we will cover below.
How to opt out of credit trigger leads.
There are three methods you can use to reduce unwanted pre-screened credit and insurance offers.
Opt out of credit trigger leads: Visit www.optoutprescreen.com to opt out of offers. This is the official site used by the Consumer Credit Reporting Industry. You can choose whether to opt out for 5 years, or permanently.
Add your number to the Do Not Call registry: Register your phone numbers with the National Do Not Call Registry. This reduces unwanted sales calls across multiple industries, not just from lenders.
Stop unsolicited mail offers: Sign up at www.dmachoice.org to reduce direct mail marketing.
Strengthening how we share borrower information.
Separate from this investigation, Lendio has also completed a broader tightening of how borrower information is shared with our lending and service partners. In a limited set of partner relationships, borrower contact information could previously be passed along directly as part of connecting borrowers to financing options, without an additional consent step from the borrower first. We’ve moved away from that model entirely.
Today, your information is only shared with a partner in one of two ways: as part of a financing package submitted to get you an offer, or after you’ve explicitly consented to be connected with a specific partner. This change was driven by our own review of partner data-sharing practices, reinforced by requirements from communication partners, and reflects our broader commitment to reducing unnecessary borrower data exposure.
Our ongoing commitment to privacy.
To be clear about what we do and don’t do: Lendio does not sell your personal financial data (the information you provide as part of a loan application) to third parties. However, like most online platforms, we do share limited information (such as identifiers and browsing activity) with advertising partners for cross-contextual behavioral advertising purposes. This is disclosed in our Privacy Policy, and you have the right to opt out at any time using our online opt-out form.
When it comes to non-advertising third parties, such as tax preparation services or other ancillary partners, your information is only shared after you have actively elected to pursue their services and provided consent. We do not share it without your knowledge.
Our data practices are governed by applicable federal and state privacy laws, including the Gramm-Leach-Bliley Act (GLBA) and the California Consumer Privacy Act (CCPA). If you have questions about how your data is used, or want to exercise your privacy rights, we want to hear from you directly.
Controlling your data at Lendio.
We take safeguarding your data and privacy very seriously at Lendio. Your data belongs to you, and you have real options to manage it.
If at any time you wish to update, access, retain or delete your data from Lendio, you can do so in your account or by contacting our team:
The SBA does not set minimum credit score requirements for SBA loans.
Instead, the U.S. Small Business Administration requires SBA-approved lenders to evaluate a borrower’s overall creditworthiness and financial stability using prudent commercial lending standards. Credit score is one factor in that evaluation, but it is not the only factor. Acceptable credit profiles may vary by lender and SBA loan program.
Because lenders retain responsibility for underwriting SBA-backed loans, different lenders may weigh credit history differently based on risk tolerance, loan structure, and the borrower’s broader financial profile.
Quick Summary: SBA loans and credit scores.
The SBA does not publish minimum credit score cutoffs.
SBA lenders assess credit as part of a broader financial review.
Both personal and business credit history may be considered.
Cash flow, debt obligations, and business stability often matter as much as credit.
Credit expectations vary by lender and SBA loan program.
In Lendio’s own funded-loan data, approved SBA 7(a) borrowers show a wide range of credit profiles, with a median score around 756.
Why credit still matters for SBA loans.
SBA loans are partially guaranteed by the federal government, but lenders still carry risk and are responsible for repayment outcomes. As part of standard underwriting, lenders review a borrower’s credit history to better understand financial behavior and repayment reliability.
Credit reports help lenders evaluate factors such as:
Payment history and consistency
Existing debt obligations
Credit utilization and account management
Patterns that may signal financial stress or stability
A stronger credit profile can help reinforce an application, but weaker credit does not automatically disqualify a borrower if other aspects of the business are strong. It can, however, affect the interest rate a lender offers. See current SBA loan interest rates for how pricing works in practice.
How SBA lenders use credit scores in practice.
While the SBA does not establish minimum credit score requirements, many SBA-approved lenders apply internal credit benchmarks or evaluation standards as part of their standard underwriting process. These benchmarks are set by individual lenders based on risk management policies and are not dictated by the SBA. As a result, acceptable credit profiles may vary from one lender to another.
SBA lenders typically also evaluate credit in context.
That means credit history is reviewed alongside:
Business cash flow and ability to service debt
Time in business and operating stability
Existing liabilities and obligations
Management experience and ownership structure
Collateral, when applicable
In some cases, strong cash flow or collateral may help offset a less-established credit profile. In others, credit concerns may prompt a lender to request additional documentation or structure the loan differently.
Does credit evaluation differ by SBA loan program?
While the SBA does not assign credit score requirements to specific loan programs, lenders may apply different underwriting approaches based on the loan type.
For example:
SBA 7(a) loansare commonly evaluated based on overall repayment ability, including cash flow, credit history, and business fundamentals.
SBA 504 loans may involve additional scrutiny due to their real estate focus and lien structure.
SBA Microloans are often administered by nonprofit intermediaries that emphasize business readiness, planning, and local economic impact alongside credit considerations.
These differences reflect lender practices, not SBA-imposed credit thresholds.
Where funded SBA 7(a) borrowers’ credit scores actually fall.
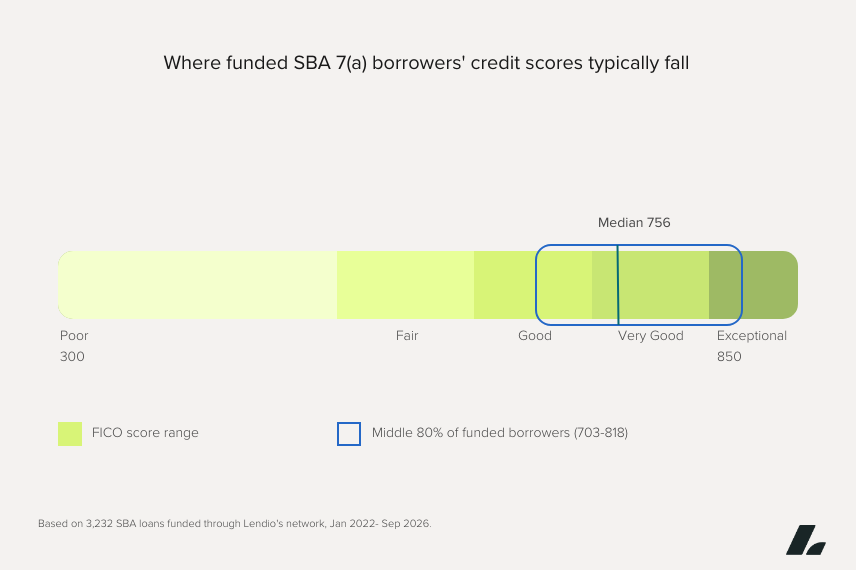
To see how these standards play out in practice, Lendio analyzed 3,232 SBA 7(a) loans funded through its network between January 2022 and September 2026.
The data shows funded borrowers span a wide range of credit profiles, although they tend to cluster towards the higher end. The median credit score among approved 7(a) borrowers was 756, with the middle 80% of funded loans falling between 703 and 818. This range runs from “Good” to “Exceptional” on standard FICO scoring.
Nearly 80% of funded SBA 7(a) loans studied carried a score of 720 or higher. At the same time, almost 1 in 5 funded borrowers had a score below 720, and a small but notable share (2%) were approved with a score under 680.
What lenders look for beyond credit scores.
Credit is only one piece of an SBA loan application. Lenders often review a combination of financial and operational factors, including:
Overall credit profile and payment history
Current cash flow and projected income
Existing business and personal debt
Financial statement and tax returns
Owner equity invested in the business
Business plan and growth outlook
Collateral, when required by the program
A well-prepared application that demonstrates financial stability can help lenders feel confident even when credit history is not perfect.
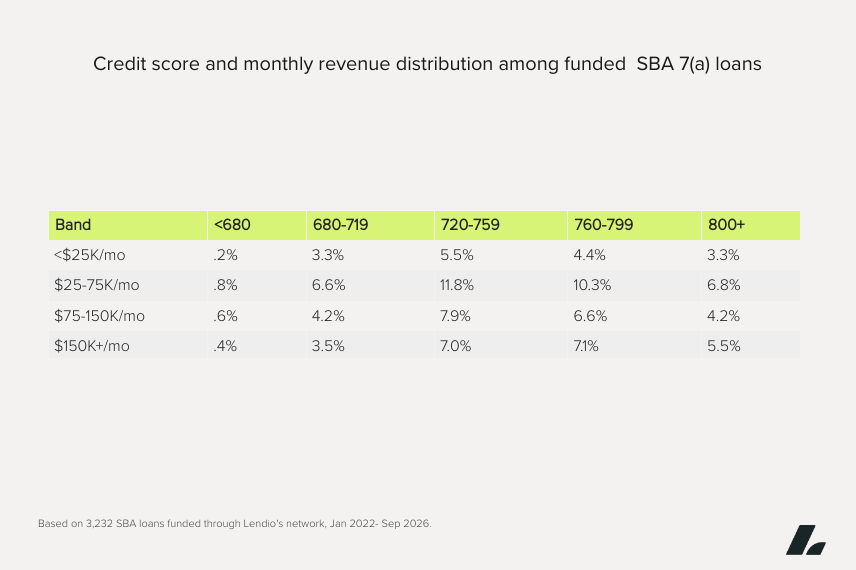
Credit score and revenue don’t move together the way you’d expect.
Looking at credit score and monthly revenue together across Lendio’s funded SBA 7(a) loans, the two don’t correlate as tightly as many applicants assume. The largest percent of funded loans sits in the middle of both ranges. Moderate to strong revenue paired with credit scores in the high 600s to 700s holds the largest percent of funded SBA 7(a) loans in the study, but funded loans appear in nearly every combination of the two.
Strengthening your credit profile before applying.
If you’re preparing to apply for an SBA loan, improving your credit profile may strengthen your application. Common preparation steps include:
Reviewing personal and business credit reports for accuracy
Addressing outstanding delinquencies or past-due accounts
Reducing outstanding debt when possible
Avoiding unnecessary new credit inquiries
Maintaining consistent, on-time payments over time
These actions support a stronger overall financial picture rather than targeting a specific score.
Can you still qualify with lower or limited credit history?
Some borrowers with limited or imperfect credit histories may still qualify for SBA financing, depending on the lender and program. Lenders may consider additional strengths such as:
Consistent business cash flow
Valuable collateral or equity contribution
Several years of operating history
Strong management experience
Clear financial documentation and projections
Lendio’s funded loan data reflects this in practice. Businesses with credit scores below 680 have been approved for SBA 7(a) financing across every monthly revenue range in the data, from under $10,000 to over $200,000 a month in average monthly sales. Score alone didn’t determine the approval outcome in these cases: the surrounding financial picture did.
Because underwriting standards vary, outcomes can differ from lender to lender.
Credit is one part of the SBA loan equation.
When it comes to SBA loans, credit score alone does not determine eligibility. For the full list of what lenders evaluate, see our guide to SBA loan eligibility requirements. Lenders assess credit as part of a broader review of financial health, business stability, and repayment capacity.
Understanding how lenders evaluate credit (and preparing your full financial profile accordingly) can help you approach the SBA loan process with clearer expectations and stronger readiness.
An SBA microloan is a government-backed small business loan of up to $50,000, funded by the U.S. Small Business Administration and issued through a network of nonprofit intermediary lenders.
Maybe you’re a year into a bakery and need a second oven. Maybe you’re launching a mobile detailing business with no credit history to speak of. Maybe you run a nonprofit childcare center and the classroom furniture has seen better days. SBA Microloans exist for exactly these types of situations: small, specific funding needs that are too small for traditional banks to bother with, but too important to put off.
Who SBA microloans are built for.
Most banks aren’t set up to underwrite a $10,000 or $15,000 loan to a brand new business with limited credit history. The paperwork and underwriting take just as long as they would for a much larger loan, and the return is smaller, so a lot of banks simply pass. The SBA built the microloan program to close the gap.
Instead of lending directly to small businesses, the SBA funds a network of intermediary lenders: community-based nonprofit organizations with experience in both lending and business technical assistance. These intermediaries make the loans, set their own credit standards within SBA guidelines, and often pair the financing with mentoring, training, or workshops. That’s one of the major benefits of the program: reaching the businesses traditional lenders frequently turn away, and fostering their success.
An SBA microloan is worth a look if you’re:
Starting or expanding a small business and need less than $50,000. According to the SBA, the average microloan is around $13,000.
A woman, minority, veteran, or low-income entrepreneur looking for capital from a mission-driven lender (see also microloans for women-owned businesses).
A startup without the time-in-business history conventional lenders usually require
Running a nonprofit childcare center that needs working capital or equipment funding.
A $10,000-$25,000 request with a thin credit file is often too small or early-stage for a conventional bank loan, but it’s a routine request for an SBA intermediary lender.
What an SBA microloan can be used for.
SBA microloans are meant for the everyday costs of rebuilding, reopening, repairing, or improving a business. Eligible uses include:
Working capital
Inventory or supplies
Furniture or fixtures
Machinery or equipment
That covers a lot of ground. The bakery owner’s second oven and part-time decorator hire, funded with roughly $18,000 and a 660 credit score is a fit. So is the childcare center’s $25,000 request to replace classroom furniture, restock supplies, and add a small playground structure; nonprofit childcare centers are one of the few types of nonprofits explicitly eligible for SBA financing (see our guide to SBA loans for nonprofits). The detailing business owner asking for $10,000 in working capital, with no time in business but solid cash flow projections and some personal collateral to offer, is closer to realistic approval than they might expect from a conventional bank.
There are limits, though. You can’t use an SBA microloan to:
Pay down existing debt
Settle lawsuits, trade disputes, fines, or penalties
Purchase real estate
Cover personal, non-business expenses
If real estate or debt refinancing is what you actually need, an SBA 7(a) loan is usually the better fit.
Note: These scenarios are illustrative examples of how the program can be used, not specific approval outcomes.
Qualifying for an SBA microloan.
In addition to SBA eligibility rules, every intermediary lender sets its own underwriting standards, so the honest answer is “it depends on who you apply with”. But most look at a similar set of things:
Business type: For-profit small businesses and certain nonprofit childcare centers are eligible.
Ownership and citizenship: 100% of direct and indirect owners must meet SBA citizenship rules for microloans (see below).
Credit profile: Most intermediaries prefer a personal credit score of 620 or higher, though many will accept lower scores. See our full breakdown of SBA loan credit requirements.
Cash flow: Current cash flow or realistic cash flow projections that show you can repay the loan
Collateral and personal guarantee: Most intermediaries require collateral plus a personal guarantee from the business owner
Location: Your business must operate within the intermediary lender's geographic service area
Time in business: No SBA-wide minimum, but individual lenders may have their own thresholds
Under SBA Policy Notice 5000-877232 and the revised SOP 52 00, microloans may only go to businesses owned 100% by U.S. Citizens or U.S. Nationals whose principal residence (per IRS Publication 523) is in the U.S., its territories, or possessions.
The following groups are not eligible under the revised rule:
Lawful Permanent Residents (green card holders, both unconditional and conditional)
DACA recipients, asylees, and refugees
Visa holders and non-resident aliens
Citizens of the People's Republic of China or Hong Kong
U.S. citizens or nationals whose principal residence is outside the U.S. or its territories
These restrictions also apply to SBA-funded Technical Assistance provided to microborrowers. If your ownership structure includes anyone outside these categories, talk to an intermediary directly before you apply. It’s better to know upfront than to lose time on an application that can’t move forward.
Feature
SBA microloan
Loan amount
Up to $50,000 (average about $13,000)
Loan structure
Term loan (lines of credit not permitted)
Repayment term
Up to 7 years
Interest rate range
Typically 8%-13%
Packaging fees
Up to 3% of loan amount, plus closing costs set by the intermediary
Funded by
SBA funds nonprofit intermediary lenders, who fund the borrower
Use of funds
Working capital, inventory, supplies, furniture, fixtures, machinery, equipment
Restricted uses
Existing debt, real estate, legal settlements, personal expenses
Interest rates and fees vary by intermediary, but the SBA caps both the maximum loan amount and the packaging fee. And unlike some other SBA programs, which can be structured as either a term loan or a line of credit, microloans are always a term loan.
So what does that mean for your monthly budget? Using a representative rate of 10% (the midpoint of the typical 8%–13% range) over the maximum seven-year term, a $13,000 loan works out to roughly $216 a month. The $50,000 maximum, on the same terms, runs about $830 a month. Your actual payment will depend on your lender's specific rate, term, and fees, so treat these as a starting point for your own math, not a quote.
How the SBA Microloan program works.
Microloans don't come directly from the federal government to the borrower. Here's how the program flows from end to end:
SBA funds intermediary lenders. The SBA distributes program funds to a network of approved nonprofit intermediary lenders, often community development financial institutions (CDFIs).
Intermediaries set local standards. Each intermediary sets its own credit, collateral, and documentation requirements within SBA guidelines, and defines its geographic service area.
You connect with an intermediary. Use the SBA's microlender directory or Lender Match tool to find an intermediary that serves your area.
The intermediary underwrites the loan. The lender reviews the application, business plan, financials, credit, and any required collateral. Some intermediaries require borrowers to complete a workshop or training program first.
Funds are disbursed. Once approved, the intermediary issues the loan as a term loan with a fixed repayment schedule.
You repay the intermediary. Repayment goes back to the intermediary, not the SBA, over a term of up to seven years.
Technical assistance often continues. Many intermediaries provide ongoing mentoring, coaching, or technical assistance throughout the life of the loan.
Pros and cons of SBA microloans.
Pros
More accessible underwriting. Built for businesses that traditional lenders often turn away, like startups, underserved owners, and applicants with limited credit history.
Faster than other SBA loans. SBA 7(a) loans can take months. Microloans often fund in around 30 days once the application is complete, though timelines vary by intermediary.
Comparatively low interest rates. Rates typically range from 8% to 13%, which usually compares favorably to short-term online lenders and merchant cash advances. (For context on the wider SBA program, see current SBA loan interest rates.)
Manageable repayment terms. Up to seven years, which keeps monthly payments more affordable for early-stage businesses.
Technical assistance included. Many intermediaries pair the loan with mentoring, coaching, or training at no extra cost.
Cons
$50,000 cap. If you need more capital, the microloan program won't get you there. Compare SBA microloans vs. 7(a) loans to see if you’re better served by a 7(a) loan.
Spending restrictions. You can't use the funds to refinance debt, buy real estate, or cover personal expenses.
Fees vary by lender. The SBA caps the packaging fee at 3%, but individual lenders can charge their own application, processing, or closing fees.
Geographic limits. Not every intermediary serves every area, and coverage in rural regions can be thin.
Citizenship restrictions tightened in 2026. The updated SOP 52 00 excludes green card holders, DACA recipients, and other groups previously eligible.
Where to find a Microloan lender (and other options).
The SBA has hundreds of intermediary lending partners around the country, and provides a comprehensive list of microloan lenders to help you find a match in your area.
Most intermediaries will want you to speak with a lending specialist by phone or apply in person, and they'll walk you through the specific paperwork and documentation they need. Some also require a workshop or training program as part of the process. Read our guide on how to apply for an SBA loan for a deeper look at how to prepare.
Note: Lendio's marketplace doesn't include microloan intermediaries directly, since they're a separate nonprofit lending network outside our lender base. But if a microloan route doesn't pan out, or you'd rather compare options before committing, Lendio works with SBA-approved lenders offering SBA 7(a) Express loans and 7(a) small loans, both available up to $50,000. They're underwritten more like a traditional bank loan than a mission-driven nonprofit lender, but feature many of the positive aspects of the SBA 7(a) loan program, including longer repayment terms, and better interest rates, so it's worth comparing both paths side by side before you decide.
If you’re interested in more SBA financing options, including SBA 7(a) standard loans up to $5 million, apply through the Lendio Marketplace. It takes just 15 minutes to apply, and you’ll be able to see multiple financing options including SBA financing (for qualifying borrowers) that fit your business profile.
Summary and key takeaways.
The SBA Microloan Program provides small-dollar, government-backed financing (up to $50,000) to startups and underserved businesses through a network of nonprofit intermediary lenders.
Average microloan is around $13,000; maximum is $50,000
Interest rates typically range from 8% to 13%; terms run up to 7 years
Funded by the SBA, issued by nonprofit intermediary lenders (often CDFIs)
As of April 1, 2026, 100% of business owners must be U.S. Citizens or U.S. Nationals with a U.S. principal residence
Funds can cover working capital, inventory, supplies, furniture, fixtures, machinery, and equipment, but not real estate or existing debt.
An SBA Express loan is a government-backed small business loan of up to $500,000 that comes with a streamlined application and a faster SBA decision than other SBA 7(a) loans.
Like other SBA loans, Express loans offer low interest rates and flexible repayment terms, but the appeal here is speed: your lender makes a credit decision and underwrites themselves, speeding the process along in comparison to other SBA 7(a) loans that require SBA review.
Let's take a closer look at what SBA Express loans are, how they work, and what it actually takes to get one, so you can decide if this is the right SBA option for your business.
What is an SBA Express loan?
An SBA Express loan is part of the SBA 7(a) loan program, the SBA's most popular funding option. Once your lender approves you, you can use the funds for commercial real estate, equipment, working capital, debt refinancing, business acquisition, or general business expansion.
What sets Express loans apart is delegated authority: the SBA gives approved lenders authority to make the credit decision and underwrite the loan themselves without SBA review*. That's what makes the faster turnaround possible. Your lender isn't waiting on a government reviewer, since they're using their own underwriting instead.
SBA Express loans cap out at $500,000, well under the maximum amounts available on a standard 7(a) loan. Repayment terms and duration depend on the loan's purpose: up to 25 years for real estate, up to 10 years for working capital, equipment, and lines of credit. Interest rates are capped by the SBA on a sliding scale based on loan size, and they get better (lower) as the loan amount goes up.
*While lenders determine creditworthiness, loan amount,and loan structure under their own underwriting standards, the Express Lender's analysis is subject to SBA review when the lender requests guaranty and/or when the SBA is performing oversight activities.
How SBA Express loans work
You apply for an SBA Express loan through an SBA-approved lender (a bank, credit union, or online lender with Express delegated authority). Two things are required regardless of lender: SBA Form 1919 (borrower information) and an owner/personal financial statement. Some lenders take on SBA Form 413, and others use their own equivalent form. Beyond that, lenders are free to use their own applications and internal underwriting, which is what keeps the process quick.
Collateral only comes into play above $50,000. Under that, the SBA doesn’t require it at all. If you’re above that threshold, the lender sets the policy, which usually means a lien on business assets. See our full breakdown of SBA loan collateral requirements for more detail on how that typically works.
SBA Express Loan details at a glance.
Factor
SBA Express Loan
Loan structure
Can be structured as a term loan, or a revolving line of credit
Maximum SBA guarantee
50%
Loan amount
Up to $500,000, though individual lender caps may apply
Available through Lendio Marketplace?
Up to $50,000. For $50,001-$500,000 in Express financing, you'll need an SBA-approved lender outside of Lendio's network, or to explore 7(a) standard offerings in the marketplace
Repayment terms
Up to 10 years for working capital, equipment, and lines of credit; up to 25 years for real estate
Not an SBA requirement, however equity injection expectations are set by the lender (typically for startups or ownership changes)
Collateral
Not required by the SBa for loans of $50,000 or less. Above this threshold, lenders set their own collateral policy
Fees
SBA guaranty fee based on loan size (waived for veteran-owned businesses in FY2026), plus any lender servicing or packaging fees
Funding times
The SBA issues a loan number within 36 hours; lenders underwriting process can vary
SBA Express vs. other SBA 7(a) options.
SBA Express is one of several ways to access the 7(a) program, and the differences mostly come down to loan size, guarantee, and how fast the lender can decide.
Program
Max amount
SBA guarantee
SBA decision
Best for
Standard 7(a)
$5 million
75%-85%
5-10 business days
Larger financing needs, real estate, acquisitions
SBA Express
$500,000
50%
Not required for underwriting
Speed, for borrowers who need $500,000 or less
The tradeoff is straightforward: Express loans trade a lower SBA guarantee (which can mean stricter lender credit standards) for a much faster decision and a lighter application. If you need more than $500,000, that's the better fit.
You can also structure the loan into a revolving express line of credit, or a term loan. This gives you a lot of flexibility, particularly if your needs are working capital rather than big one-time purchases.
Financing under $50,000? SBA Express loans are available in the Lendio marketplace. It's also worth comparing Express loans against SBA microloans, which use a different lender network and underwriting approach entirely.
Eligibility requirements
Every SBA Express loan has to clear the SBA’s general core requirements, plus any additional criteria your lender applies. Lenders layer their own standards on top, including credit score, time in business and revenue requirements.
Because of this, it’s worth shopping around rather than assuming one no means you’re out of options everywhere. For the full breakdown of the SBA requirements (plus common lender standards on top of these), see our SBA loan eligibility requirements guide.
How to take out an SBA Express loan.
If you’re ready to move forward, here’s the general path (see our full guide on how to apply for an SBA loan for more detail on any step):
Determine your borrowing needs. SBA Express loans cap out at $500,000, so if you need more, you’ll want to look at a standard 7(a) loan instead (available in the Lendio Marketplace). If you need under $50,000, SBA Express loan options are available in the Lendio Marketplace, and you can also assess whether an SBA Microloan might serve your needs.
Choose a lender. Not every SBA lender operates the same way. Make use of a marketplace to shop around, or use the SBA's Lender Match tool to get connected.
Complete SBA Form 1919. Be ready to share ownership details, intended use of funds, employee counts, and any prior SBA loan history. Double-checking this paperwork before you submit it is one of the easiest ways to keep your timeline on track.
Submit your lender's required documentation. This often includes financial statements, tax returns, and a business plan, depending on how your lender underwrites.
Your lender makes the credit decision. Once they approve the loan internally; they submit it through SBA’s E-Tran system to get a loan number. Final funding timelines then depends on your lender’s own closing process.
Pros and cons of SBA Express loans.
Pros
Fast decisions: Delegated authority to your lender makes approval and underwriting much faster than files that require SBA review.
Lighter documentation: Lenders can use their own forms and underwriting, so the application is simpler than a standard 7(a) loan.
No collateral under $50,000: Smaller loans don't require the SBA to take collateral at all.
Cons
Lower borrowing cap: $500,000 may not cover a large equipment purchase or acquisition. A standard 7(a) loan goes up to $5 million.
Lower SBA guarantee: At 50%, lenders carry more risk than they would with a standard 7(a) loan's 75%–85% guarantee, which can translate to stricter credit requirements.
Funding timelines can vary. Depending on your lending partner, approval and funding goes as quickly as their underwriting process does. You could see a wide range of funding timelines.
Bottom line.
If you want an SBA loan without the lengthy application and approval times of a standard 7(a) loan, the SBA Express loan is worth a close look. Weigh the tradeoffs (a lower borrowing cap and guarantee in exchange for real speed) against your needs. If you’re interested in pursuing SBA loan options for your business, apply through Lendio. The application takes less than 15 minutes, and you can compare SBA 7(a) loans and other forms of financing to make the most informed decision for your business.
The SBA 504 loan program is primarily designed to help small businesses purchase or improve commercial real estate or long-term heavy equipment or machinery through a fixed-rate, long-term loan structure.
The program is administered by the U.S. Small Business Administration (SBA) and funded through a three-way partnership: a traditional lender, a Certified Development Company (CDC), and the borrower. If you’re a growth-stage business planning to buy a building, put up a new facility, or invest in equipment you’ll use for years to come, this is one of the more affordable ways to finance that kind of project.
As of 2026, the maximum SBA 504 loan amount is $5.5 million for most projects (with higher thresholds applied to certain manufacturing and energy-related projects).
When to use an SBA 504 loan.
A 504 loan tends to make the most sense when you’re not just solving a short-term cash need. Other SBA loan programs, such as the 7(a) loan program, may be a better fit in that case. Instead, an SBA 504 loan can support you when you’re making a real bet on where your business is headed with growth, expansion or enhanced capacity.
The 504 loan program is a good fit when you:
Want predictable monthly payments through a fixed interest rate, rather than a rate that can move on you mid-project.
Are planning a long-term expansion, such as buying, building, or upgrading (not covering a temporary cash flow gap).
Need financing for assets central to how you operate, like a building or major equipment.
How SBA 504 financing is structured.
Here’s what makes a 504 loan different from a typical bank loan: instead of one lender, you’re working with three parties, each covering a piece of the project. It’s often called the 50/40/10 structure:
A traditional lender covers at least 50% of the project cost, in first-lien position
A CDC covers up to 40% through an SBA-guaranteed debenture (this is essentially a bond the CDC sells to investors, backed by the SBA)
You, the borrower, cover at least 10% as equity
The borrower share can run higher in some cases. It’s commonly 15% if you’re buying a special-purpose property, such as a hotel or gas station, or if your business is under two years old. When both apply, it’s commonly 20% borrower share.
Typical 504 structures
Standard financing structure
New Business OR Special Purpose Property
Both New AND Limited or Special Purpose Property
Third Party Lender
50
50
50
CDC/SBA
40
35
30
Borrower
10
15
20
For example, if you’re buying a $2 million owner-occupied warehouse, you might see roughly $1 million financed by a bank, $800,000 financed through the CDC/ SBA, and $200,000 coming from you as a down payment.
On rates: The lender’s portion can be fixed or variable depending on the bank, but the CDC/ SBA portion is fixed for the life of the loan, which is a big part of the appeal. Rates move monthly with 10-year treasury yields, so check out our roundup of current SBA loan interest rates on the CDC/ SBA debenture of the loan in comparison to other SBA loan programs.
On terms: Repayment runs 10, 20, or 25 years depending on what you’re financing. Real estate usually qualifies for the longer end, and equipment tends to land around 10 years. For how that stacks up across SBA programs, see SBA loan terms and duration.
What SBA 504 loans can be used for.
Think of the SBA 504 loan program as purpose-built for anything long-term and asset-based. That generally covers three broad categories.
Real estate: Buying owner-occupied commercial real estate (see SBA real estate loan options for how SBA 504 stacks up against other paths), purchasing existing buildings, constructing new ones, expanding, or renovating a facility you already operate out of, and acquiring land as part of an eligible project. The 504 loan cannot be used for purchasing real estate for speculation or resale.
Site work: Grading and preparing land, adding streets, access roads, or parking, landscaping and drainage, and some community improvements like curbs or sidewalks (usually capped at a small share of total project cost).
Long-term equipment: Fixed equipment with a useful life of at least 10 years, generally permanently installed at a specific location. Occasionally, short-term financing for equipment or furnishings is allowed too, but only when those items are essential to the project and a minor slice of the overall cost.
What SBA 504 loans can’t be used for
On the flip side of that long-term focus is a firm line around what doesn’t qualify as eligible use of proceeds. This is usually where people get tripped up, and in some cases, may be better served by a more flexible SBA program.
Working capital and day-to-day expenses: Payroll, rent, utilities, inventory, supplies, or any short-term cash flow need.
Most debt refinancing: You generally can’t refinance existing debt that isn’t tied to eligible fixed assets, or refinance purely to free up working capital.
Investment or passive real estate: Rental properties, property your business doesn’t primarily occupy, or speculative purchases.
Intangible assets: Business goodwill, software or cloud services, or intellectual property.
Land speculation: Vacant land for future developments, land beyond your current operational needs, or land meant for resale or lease to someone else.
The main takeaway here that’s most important to remember is: SBA 504 loans don’t cover working capital, inventory, or operating expenses, even though SBA 7(a) loans often do. That’s the cleanest way to distinguish which program is going to suit your needs. You can put 7(a) funds toward most of what 504 covers, but not the reverse, so the right program usually comes down to what you’re actually financing, not the size of the loan or the rate.
SBA 504 loan eligibility: Specific program requirements.
SBA loan programs share the same baseline core eligibility requirements: your business needs to be a lawful, for-profit operation, meet ownership and guarantor standards, and show you can’t get comparable credit elsewhere on reasonable terms. We cover those universal requirements in full in our guide to SBA loan eligibility requirements, including how the SBA defines a small business for program purposes. If you haven’t sized your business up against those requirements yet, that’s the right place to start.
Beyond that baseline, the 504 loan program layers on a few requirements tied to what the program is built to finance: long-term, owner-occupied fixed assets. Approval specific still vary by lender and CDC, but here’s what’s unique to the program:
Owner-occupancy (for real estate and construction projects): 504 loans are only for owner-occupied properties. For existing buildings, your business generally needs to occupy at least 51% of the space. For new construction, that threshold is typically 60% at the start, with an expectation that you’ll occupy 80% within 10 years. This is because 504 financing is meant to support businesses actually operating out of the property, not investors holding onto it passively.
Business stage. Most 504 borrowers are growth-stage businesses with established operations and the cash flow to support a long repayment term. Newer businesses aren’t automatically ruled out, but expect to bring more equity or documentation to the table depending on how the project is structured.
Financial review. Rather than a single pass/fail number, lenders and CDCs look at the whole picture. This includes cash flow trends, personal and business credit history, and how viable the project itself is long-term. Requirements vary by lender and CDC, but our breakdown of SBA loan credit score requirements is a good starting point for what lenders tend to weigh.
A 504 loan probably isn’t the right fit if you need working capital or flexible funding, you’re eyeing an investment or rental property, you can’t meet the owner-occupancy bar, or you’re looking for short-term or revolving credit. In any of those cases, another SBA program or a different type of financing will likely serve you better.
The economic development requirement
A piece that can trip up borrowers is the economic development requirements, because it doesn’t show up in most financing conversations. Every 504 project also has to advance at least one SBA-defined economic development goal. In practice, a CDC handles most of this on your behalf, but it’s worth understanding what they’re looking for.
The most common path is job creation or retention. As of October 2025, a project generally needs to support one job for roughly every $95,000 of SBA-backed debenture (that threshold moved up from $90,000), per the SBA's updated job creation and retention rule. So a $950,000 debenture would generally need to support around 10 jobs. For small manufacturers and energy-related projects, that threshold is higher (about $150,000 per job). Job retention counts too, if a CDC can show jobs would otherwise be lost. Those jobs don't have to sit at the project site itself, though most should benefit the local community where the project is located.
If job creation doesn't apply to the project, it can still qualify through other public policy goals: community development, rural development, revitalizing a business district, expanding in an underserved area, or certain energy-efficiency and sustainability improvements. Energy-focused projects have their own bar to clear (cutting energy use by at least 10%, sourcing more than 15% of on-site energy from renewables, or documented sustainable design), typically backed by a third-party energy audit or engineering report.
None of this usually falls on you directly as the borrower. Your CDC handles the documentation and demonstrates how the project meets these goals. Your part is mostly providing project details and employment estimates when asked.
How the SBA 504 loan process works.
Because three parties are involved (a lender, a CDC, and the SBA) the process has more steps than a typical loan, but each is fairly straightforward. Here’s how the process works.
Step 1: Confirm your project fits
Make sure what you're financing is actually 504-eligible, such as owner-occupied real estate or long-term fixed equipment, not working capital or an investment property.
Step 2: Map out the total project cost
Put together your full budget. This will include purchase price, construction, renovations, equipment, and eligible soft costs, and get a sense of how the 50/40/10 split will apply to your numbers.
Step 3: Find a Certified Development Company
CDCs partner with a bank or lender to originate 504 loans, and they'll help document your project's eligibility along the way. You can find one in your state through the SBA's list of certified development companies, or use the SBA's Lender Match tool.
Step 4: Put your application package together
Expect to provide financial statements and tax returns, a current debt schedule, information on owners and guarantors, and details on the project itself. This will include property specs, equipment, construction plans, budgets. Exactly what's needed varies by lender, CDC, and how complex the deal is.
Step 5: Underwriting and eligibility review
The lender and CDC dig into whether the business and project meet 504 requirements, whether you can realistically repay, and whether the deal checks the required boxes listed above, including owner occupancy, economic development goals, and so on.
Step 6: SBA authorization
Once underwriting clears, the CDC submits everything for SBA sign-off. From there, you're headed toward closing.
Step 7: Close and fund
At closing, the deal is funded per the approved structure. For construction or renovation projects, funds often go out in phases tied to project milestones rather than all at once.
Step 8: Repayment and reporting
Repayment starts on the agreed term. CDCs also keep tabs on things like job creation as part of their ongoing SBA reporting.
Pros and cons of SBA 504 Loans.
What works in your favor:
Built for long-term investments: 504 loans are well-suited to expansion projects with lasting value, not quick turnarounds.
Fixed rates: The SBA-backed portion typically carries a fixed rate, so your payment doesn’t move around on you.
Long repayment terms: Terms commonly run 10-25 years depending on the asset, which spreads out the cost of a big purchase.
Lower down payment: Often less upfront equity required than conventional commercial real estate financing, though your specific contribution will vary.
Ties into economic development: Job creation and community investment are baked into the program’s purpose.
What to weigh against that:
Narrow use of funds: No working capital, inventory, or short-term expenses
More moving parts: A lender and a CDC both need to sign off, which adds coordination compared to a single-lender loan.
Slower approval: The layered review process usually takes longer than conventional or non-SBA financing
Owner-occupancy required: Investment or rental properties are off the table entirely.
Not built for speed: If you need capital fast or want flexibility, this probably isn’t your best loan option.
Is an SBA 504 loan right for your project?
Here are some quick questions to ask yourself to find out if this option is right for you.
Buying or building owner-occupied commercial real estate? This is one of the more common (and affordable) ways to finance it.
Expanding or renovating a facility you already operate out of? The fixed-asset portion of that project likely qualifies.
Purchasing long-term equipment that'll sit in one place for years? 504 financing can often cover that too.
Making energy-efficiency upgrades you can document with an audit or engineering report? You may qualify under the program's energy public policy track.
Want predictable payments on a large, long-term investment? That's exactly what the fixed-rate structure is designed for.
Need working capital, inventory funding, or short-term flexibility? Look elsewhere for financing. That's not what this program is built for.
Buying investment or rental property you won't primarily occupy? Same answer as above. 504 isn't the right tool here.
Summary and key takeaways.
SBA 504 loans exist for one specific job: financing long-term, fixed-asset investments like owner-occupied real estate and permanent equipment. A lender, a CDC, and SBA-backed financing come together to help eligible businesses fund projects up to $5.5 million in most cases, while also supporting expansion, job creation, and local economic development along the way. If that matches what you're trying to do, and you're building for the long run rather than solving a short-term problem, it's worth a serious look.
504 loans are for fixed assets, not working capital. Real estate, construction, renovations, and long-term equipment are eligible uses.
Financing follows a 50/40/10 split between a lender, a CDC, and you, with fixed rates that move monthly (roughly 5.9%–6.2% as of July 2026).
Eligibility is tied to the project, not just the business. Owner-occupancy and economic development goals both matter, including the updated $95,000-per-job threshold that took effect in October 2025.
504 and 7(a) loans solve different problems. The right choice usually comes down to how you'll use the money, not the loan size or rate.
This program fits growth-stage businesses best. It's less suited to early-stage companies or anyone needing short-term flexibility.
Social media can be a game-changer for small businesses—if you know how to use it. This guide covers everything from choosing the right platforms to creating engaging content and growing your audience. With actionable tips and proven strategies, you’ll learn how to turn likes and follows into real business results.
Email marketing is one of the most powerful tools for small businesses—when done right. This guide covers everything from building your email list to crafting engaging campaigns that drive results. With actionable tips and step-by-step guidance, you’ll learn how to connect with your audience, boost sales, and grow your business through email.
Digital marketing doesn’t have to be overwhelming. This guide simplifies the essentials, from building an online presence to leveraging social media, email, and SEO. Packed with practical tips and step-by-step strategies, it’s designed to help small businesses succeed in the digital world without a big budget or a full marketing team.
Let’s face it. There’s a lot of bad marketing advice out there. Or great advice that’s far too in-depth for a small business owner who isn’t looking to start a full-time career in marketing. We created this guide to cut through the clutter and provide you with principles, direction and the applicable step-by-step how-tos to get the job done.
Your brand is more than just a logo—it’s the heart of your business. This guide walks you through the essentials of small business branding, from defining your identity and crafting your message to building a strong, lasting impression. With clear steps and actionable advice, you’ll create a brand that resonates with customers and sets your business apart.
Hiring for small businesses doesn’t have to be complicated. Your business can achieve success when you understand relevant legal requirements and find the right job candidates for your open positions. This comprehensive guide covers everything from finding the right employees to hire to employee training and development.
Your best customers are your biggest growth opportunity. This guide breaks down customer marketing strategies tailored for small businesses, helping you turn happy customers into loyal advocates. From building relationships to leveraging referrals, discover actionable steps to maximize lifetime value and drive sustainable growth.
From selecting the right franchise opportunity to navigating the financial aspects, this step-by-step resource equips aspiring entrepreneurs with the knowledge and strategies needed to thrive in the world of franchising.
Have a business idea but not sure where to start? Our comprehensive guide to starting a business has everything you need to know. From legal requirements to market research, we’ve got you covered.
Running and growing a business is no easy feat. Our guide to running a business has everything you need to know to keep things running smoothly. From managing employees to marketing your business, we’ve got you covered.
Take your business to the next level with our Accounting Guide. Master the language of numbers, understand financial statements, and make informed decisions based on accurate financial data. Discover the power of sound financial management.
Master the art of cash flow management with our comprehensive guide. Learn strategies to optimize your cash flow, forecast revenue and expenses, and keep your business financially stable. Take control of your finances and achieve long-term success.
Streamline your billing process with our Invoicing Guide. Learn how to create professional invoices, manage client payments, and maintain a healthy cash flow for your business. Get paid faster and efficiently track your revenue.
A great marketing strategy is the foundation of small business success. This guide takes you step-by-step through defining your goals, identifying your audience, and choosing the right channels. With practical tips and clear direction, you’ll build a tailored strategy that drives growth and delivers measurable results.
Navigate the complex world of taxes with our Tax Preparation Guide. From understanding tax obligations to maximizing deductions and filing quarterly taxes, we’ll help you stay compliant and minimize your tax burden. Unlock the secrets of tax success for your business.
Stay on top of your business finances with our Bookkeeping Guide. Learn the art of tracking income and expenses, maintaining financial records, and keeping your books in order. Unlock financial success with our expert tips.
Need help securing funding for your business? Our business loans guide simplifies the financing process, explains key terms, and walks you through your loan options.